HUD did not approve 3920 for FHA financing. Here is why.
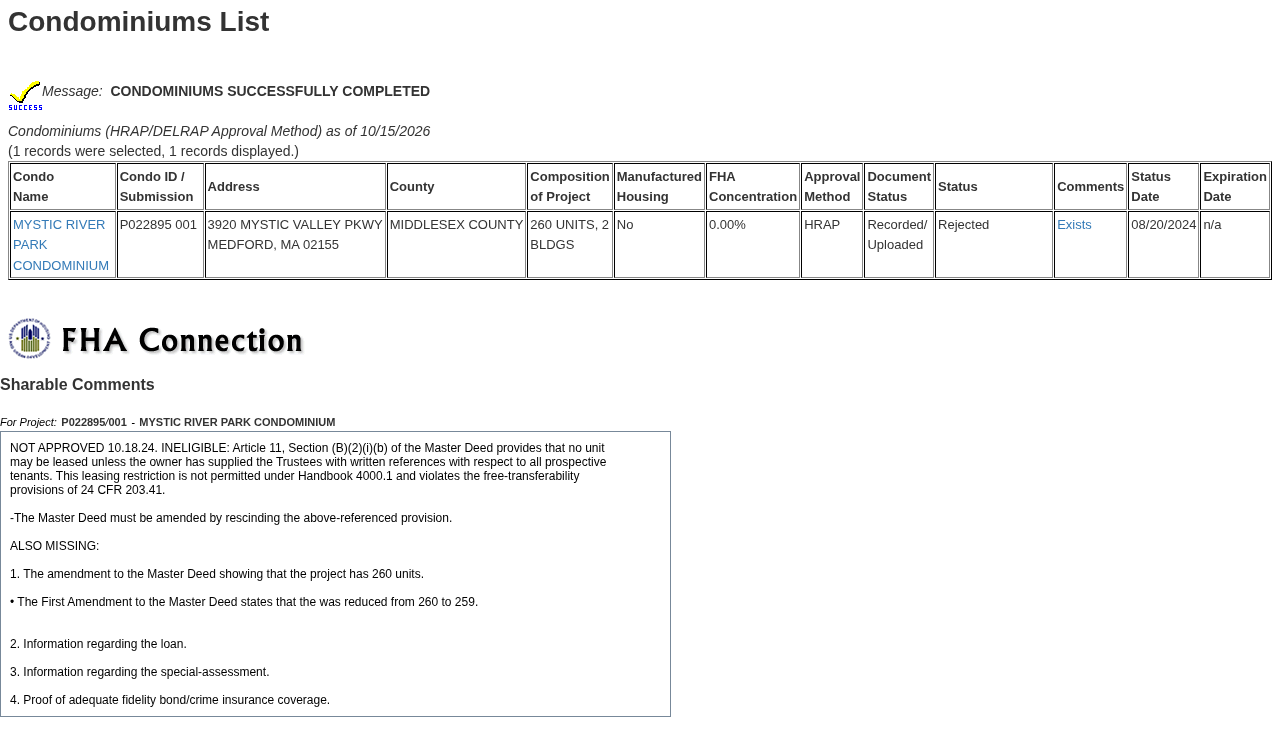
HUD’s public condo database lists Mystic River Park Condominium, 3920 Mystic Valley Parkway, Medford, MA 02155 (Condo ID P022895, submission 001), as Rejected, with a status date of 08/20/2024. HUD’s posted comments begin: “NOT APPROVED 10.18.24. INELIGIBLE.” That means a buyer generally cannot get an FHA-insured mortgage here through an approved project.
What the record says
HUD’s listing shows: 260 units, 2 buildings; not manufactured housing; FHA concentration 0.00%; approval method HRAP (HUD review); documents “Recorded/Uploaded”; status Rejected; status date 08/20/2024; no expiration date. HUD’s project page says the project “was rejected on: 08/20/2024” and was last updated 10/18/2024. It is handled by HUD’s Philadelphia Homeownership Center.
Why it was rejected, in HUD’s words
“Article 11, Section (B)(2)(i)(b) of the Master Deed provides that no unit may be leased unless the owner has supplied the Trustees with written references with respect to all prospective tenants. This leasing restriction is not permitted under Handbook 4000.1 and violates the free-transferability provisions of 24 CFR 203.41.” HUD adds: “The Master Deed must be amended by rescinding the above-referenced provision.”
HUD also listed four items as “ALSO MISSING”:
- “The amendment to the Master Deed showing that the project has 260 units.” HUD notes the First Amendment to the Master Deed says the count was reduced from 260 to 259.
- “Information regarding the loan.”
- “Information regarding the special-assessment.”
- “Proof of adequate fidelity bond/crime insurance coverage.”
The record does not say anything more about the loan or the special assessment. It says only that HUD did not receive information about them.
What FHA approval means, and who it hurts
Many first-time and moderate-income buyers use FHA loans. Federal rules say FHA-insured property must be free of “legal restrictions on conveyance”, and leases count. HUD guidance lets associations set minimum lease terms and rental caps. It says an association “may not require that a prospective tenant be approved by the condominium association and/or its agent(s).” A tenant-reference rule is the kind of clause HUD flagged here.
Without project approval, a buyer’s only FHA route is a Single-Unit Approval. HUD says this is allowed even in a Rejected project. It has limits: at most 10% of units with FHA loans in a project this size, a HUD review of each loan, and no “adverse determination” on the project’s viability. It is not clear whether a lender could clear the same Master Deed clause through that route. When fewer buyers can finance, sellers have fewer buyers, and that can weigh on prices.
What owners can ask the board
- Who submitted this to HUD in 2024, and why was no follow-up filed after the October 2024 decision?
- Will the board propose amending Article 11 to remove the tenant-reference requirement?
- Is the unit count 260 or 259, and which recorded amendment is correct?
- What loan and special assessment was HUD asking about, and what are the terms?
- Does the association carry adequate fidelity/crime coverage? Can owners see the policy?
- Does the board plan to resubmit for FHA approval, and when?
Owners can ask to see these records under c. 183A §10.
Caveat emptor.